Roof Insurance Guide for Wylie, TX
Understand the roof work, the policy terms and who decides each part. Insurance coverage and a suitable roof repair are connected but separate questions.
Understand the roof work and the insurance decision
A roof can need work even when insurance does not cover it, and a covered claim can still leave costs for the homeowner. Understanding that difference makes it easier to plan the project without confusing a roof recommendation with a payment promise.
This guide explains common Texas roof-claim terms. Your policy, the cause of damage and the insurer’s decision determine the coverage. The roof itself still needs a suitable repair or replacement scope.
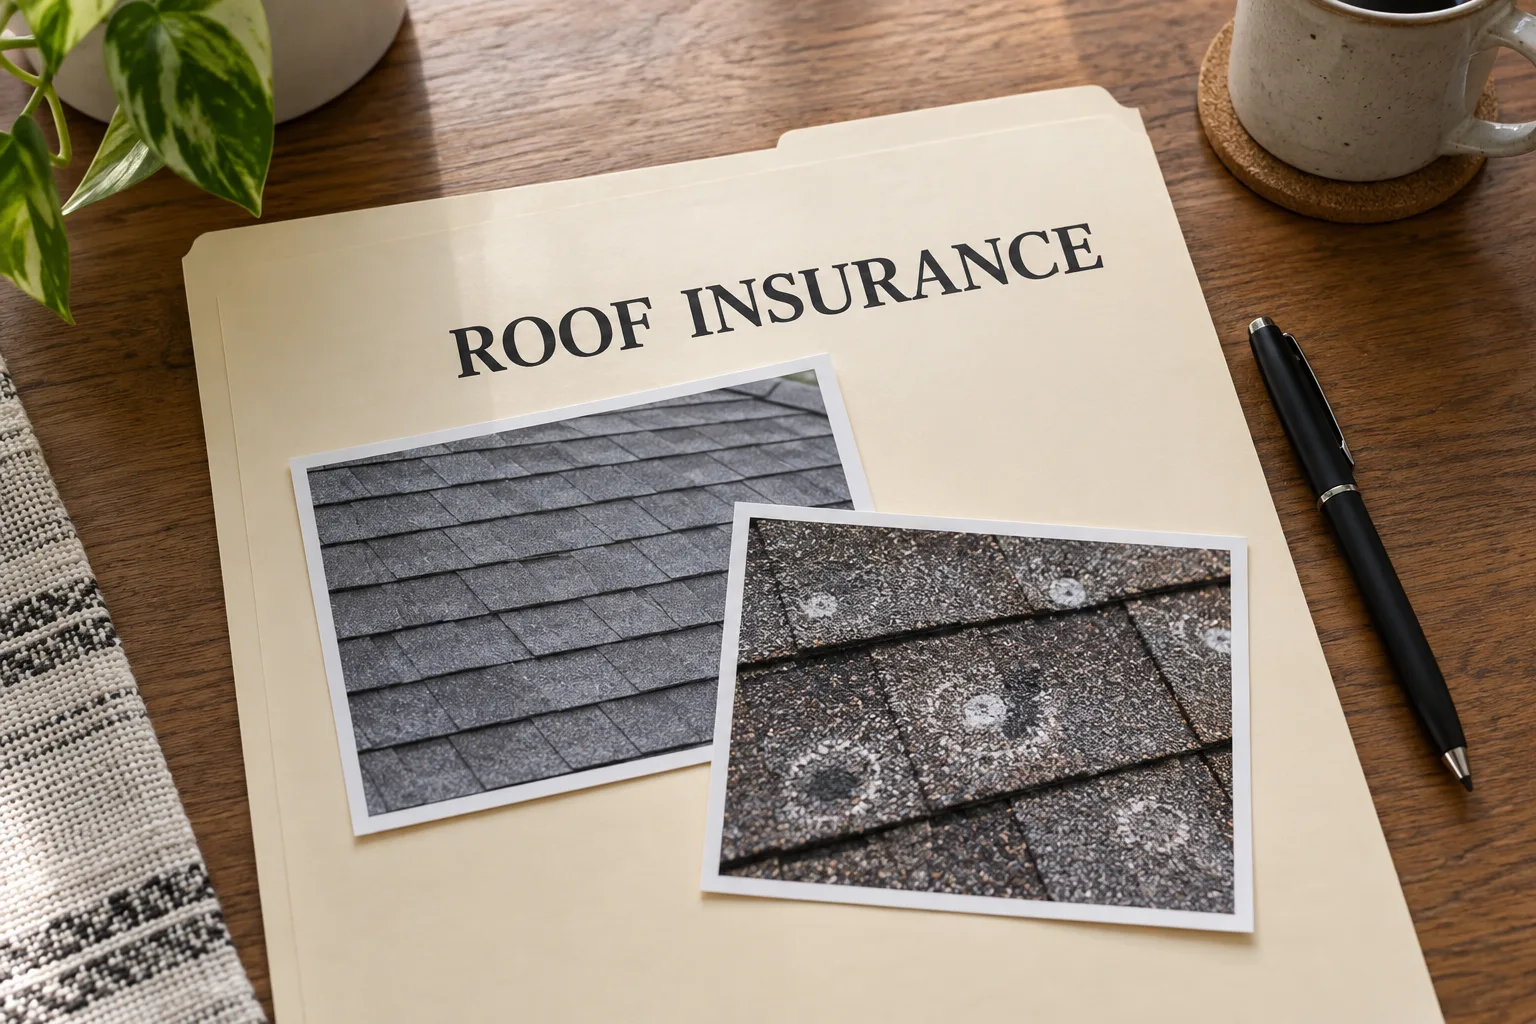
Know which part of the roof bill is yours
Your policy and insurer control the settlement. The Texas Department of Insurance roof guidance explains these distinctions.
Connect the damage to a roofing scope
The condition of the roof and the cause of damage need to be considered separately from the payment terms.
Sudden damage and ordinary wear
A storm can create damage that needs repair, but wear alone is not automatically an insured loss. The policy’s covered causes and exclusions govern.
The roofing scope
The roofer identifies the work needed to address the roof condition, including affected details and layers. That scope may change if concealed damage is found.
The coverage decision
The insurer evaluates coverage and settlement. A contractor’s recommendation does not bind the insurer, and an insurer payment does not by itself describe every construction detail.
Texas keeps roofing and claim representation separate
Texas separates roofing work from public-adjuster representation on the same claim. A roofer doing the job cannot act as the public adjuster for that roofing claim. Texas also prohibits contractors from waiving or absorbing a deductible through prohibited arrangements.
Roof condition and work
The roofer explains the damage and suitable construction scope. That assessment can inform the roofing decision without taking over representation of the insurance claim.
Coverage and settlement
The insurer applies the policy to the loss. Deductible, depreciation and settlement terms still determine the owner’s payment responsibility; the roofing contract does not erase them.
Use the official Texas roofing and insurance guidance for the legal distinction. This guide does not promise coverage, payment or claim representation.
Move through the claim and repair decisions
Keep the work and payment decisions clear as the claim proceeds.
Address the immediate roof concern
An active leak may need safe temporary protection. Keep relevant information about what happened and follow the insurer’s reporting requirements.
Connect the claim to the work scope
Have the roof assessed and understand the repair or replacement proposed. Resolve differences and changes through the appropriate contractor and insurer conversations.
Understand settlement conditions
Review the deductible, depreciation, payment stages and any receipts or work requirements. Do not assume the first payment is the final amount or that every cost is covered.
Roof insurance FAQs
Does a replacement recommendation guarantee insurance coverage?
No. The roofing recommendation addresses condition and useful work. Coverage depends on the policy, cause and insurer’s assessment.
Can the contractor waive my deductible?
Texas prohibits deductible waivers or absorption through specified contractor arrangements. Review the TDI guidance and your policy rather than treating a deductible offer as a normal discount.
Can I get help with the roof before knowing the claim result?
Yes. A free inspection can help establish the roof concern and the work options. It does not guarantee the insurer’s decision.